Banking Conditions Survey


For this survey, Eleventh District banking executives were asked supplemental questions on credit standards, loan demand and interest rates. Read the special questions results.
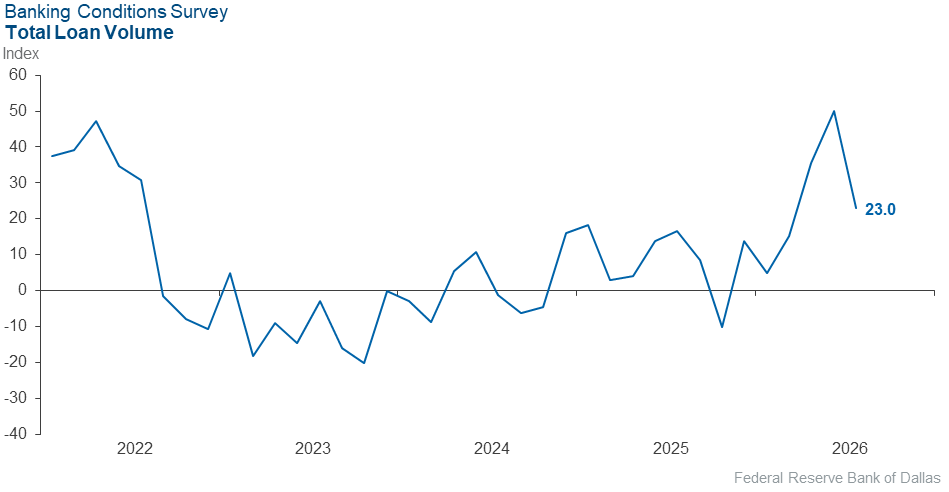
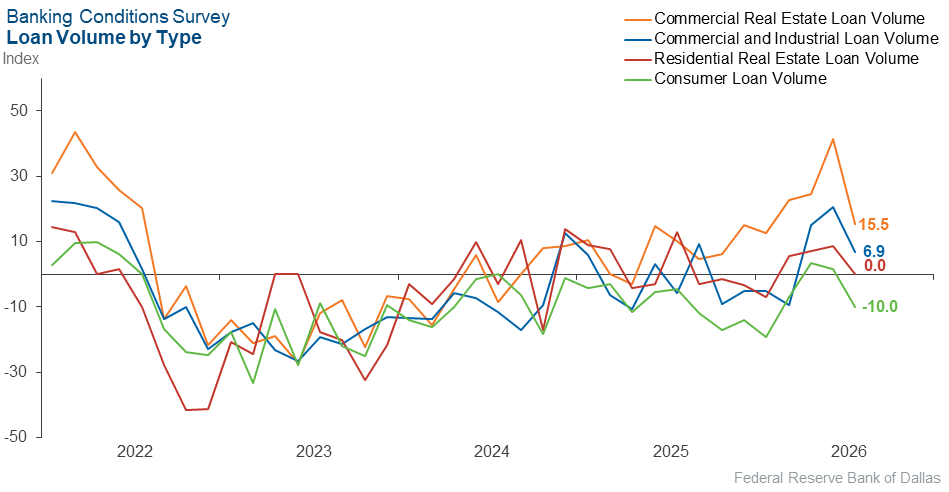
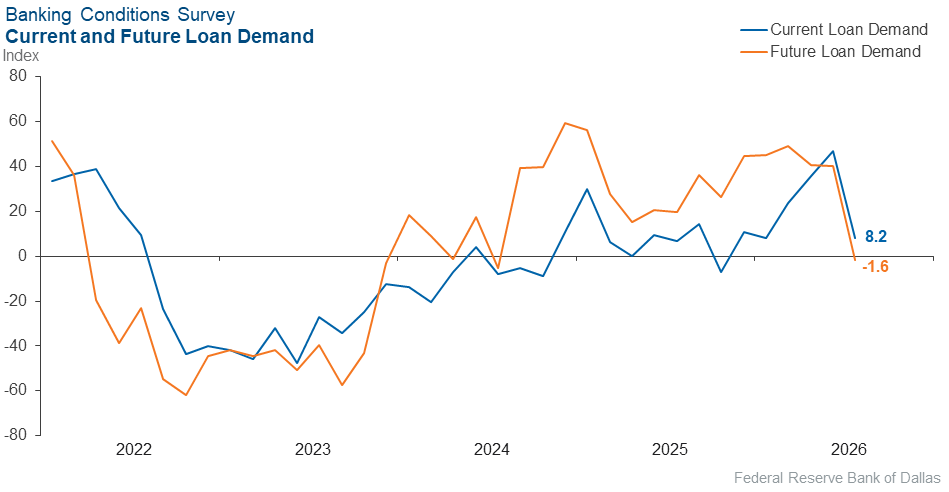
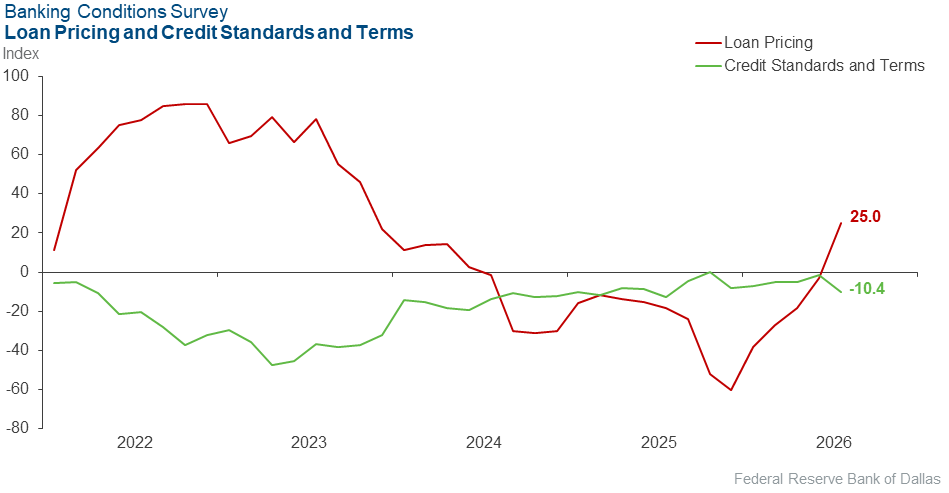
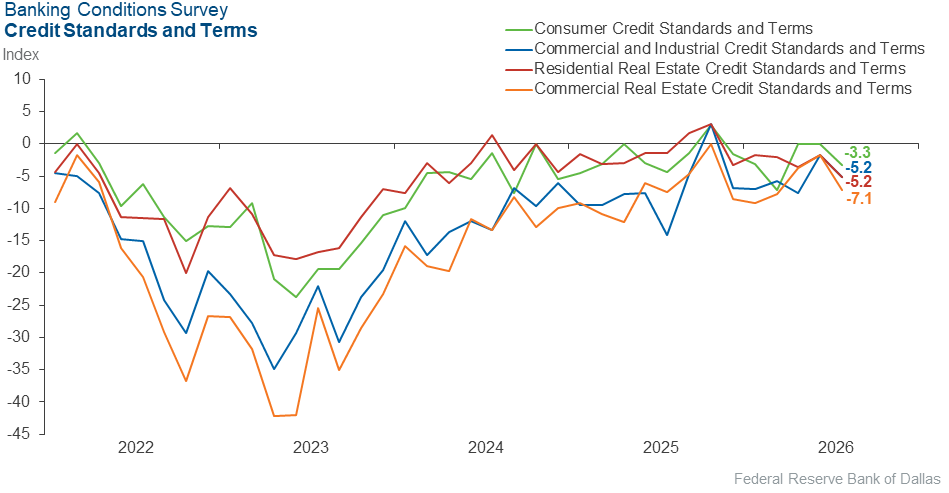
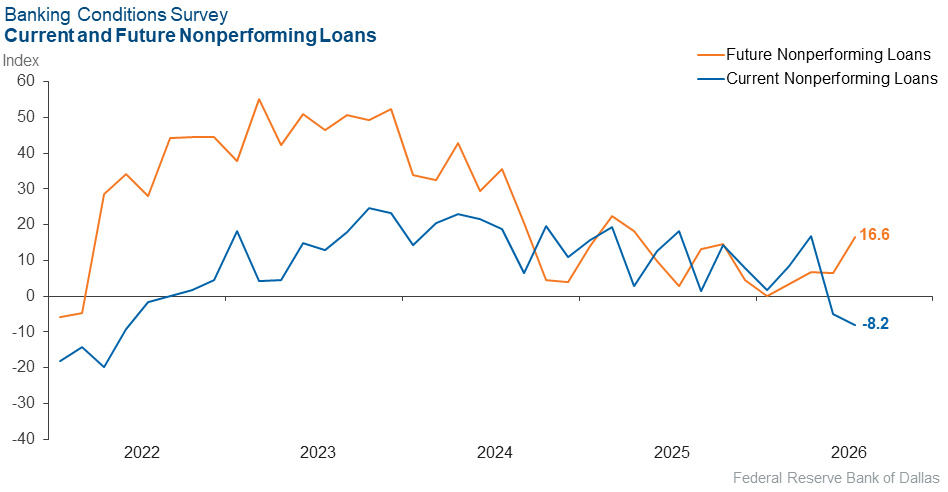
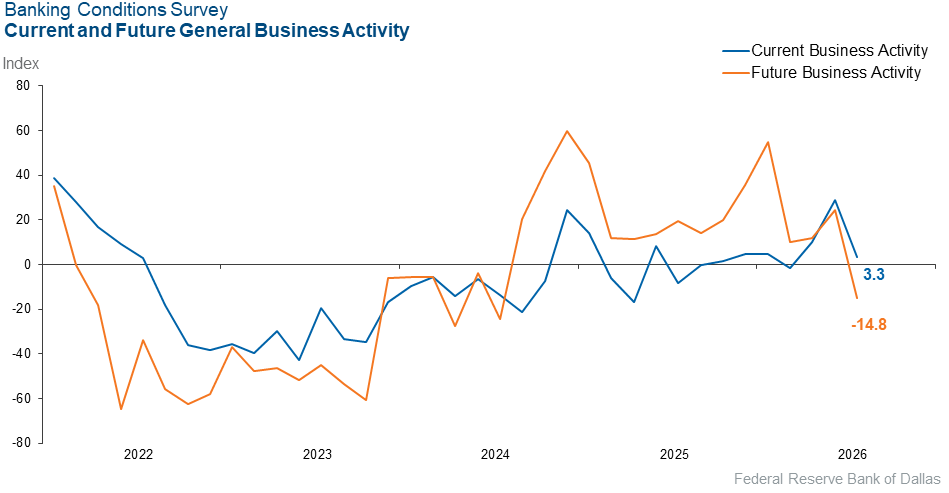
Loan volume and demand continued to grow but at a decelerated pace in September, a reversal of the six-month trend of accelerating growth. Credit standards and terms tightened and loan pricing increased. Overall loan performance improved further. Bankers reported only modest increases in general business activity on net. Outlooks turned pessimistic. Survey respondents expect a slight decline in loan demand and a moderate decline in business activity six months from now, as well as a deterioration in loan performance.
Next release: November 9, 2026
Data were collected September 15–23, and 61 financial institutions responded to the survey. The Federal Reserve Bank of Dallas conducts the Banking Conditions Survey twice each quarter to obtain a timely assessment of activity at banks and credit unions headquartered in the Eleventh Federal Reserve District. CEOs or senior loan officers of financial institutions report on how conditions have changed for indicators such as loan volume, nonperforming loans and loan pricing. Respondents are also asked to report on their banking outlook and their evaluation of general business activity.
Survey responses are used to calculate an index for each indicator. Each index is calculated by subtracting the percentage of respondents reporting a decrease (or tightening) from the percentage reporting an increase (or easing). When the share of respondents reporting an increase exceeds the share reporting a decrease, the index will be greater than zero, suggesting the indicator has increased over the prior reporting period. If the share of respondents reporting a decrease exceeds the share reporting an increase, the index will be below zero, suggesting the indicator has decreased over the prior reporting period. An index will be zero when the number of respondents reporting an increase is equal to the number reporting a decrease.
Results summary
Historical data are available from March 2017.
| Total Loans: Over the past six weeks, how have the following changed? | |||||
| Indicator | Current Index | Previous Index | % Reporting Increase | % Reporting No Change | % Reporting Decrease |
Loan volume | 23.0 | 50.0 | 49.2 | 24.6 | 26.2 |
Loan demand | 8.2 | 46.7 | 37.7 | 32.8 | 29.5 |
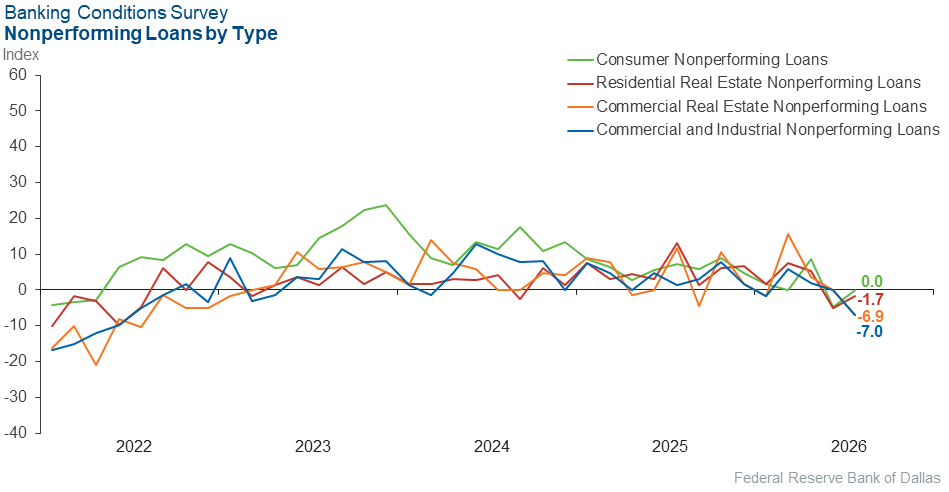
Nonperforming loans | –8.2 | –4.9 | 11.5 | 68.9 | 19.7 |
Loan pricing | 25.0 | –3.2 | 28.3 | 68.3 | 3.3 |
| Indicator | Current Index | Previous Index | % Reporting Eased | % Reporting No Change | % Reporting Tightened |
Credit standards and terms | –10.4 | –1.7 | 3.4 | 82.8 | 13.8 |
| Commercial and Industrial Loans: Over the past six weeks, how have the following changed? | |||||
| Indicator | Current Index | Previous Index | % Reporting Increase | % Reporting No Change | % Reporting Decrease |
Loan volume | 6.9 | 20.7 | 24.1 | 58.6 | 17.2 |
Nonperforming loans | –7.0 | 0.0 | 3.5 | 86.0 | 10.5 |
| Indicator | Current Index | Previous Index | % Reporting Eased | % Reporting No Change | % Reporting Tightened |
Credit standards and terms | –5.2 | –1.7 | 1.7 | 91.4 | 6.9 |
| Commercial Real Estate Loans: Over the past six weeks, how have the following changed? | |||||
| Indicator | Current Index | Previous Index | % Reporting Increase | % Reporting No Change | % Reporting Decrease |
Loan volume | 15.5 | 41.4 | 34.5 | 46.6 | 19.0 |
Nonperforming loans | –6.9 | 0.0 | 5.2 | 82.8 | 12.1 |
| Indicator | Current Index | Previous Index | % Reporting Eased | % Reporting No Change | % Reporting Tightened |
Credit standards and terms | –7.1 | –1.7 | 1.8 | 89.3 | 8.9 |
| Residential Real Estate Loans: Over the past six weeks, how have the following changed? | |||||
| Indicator | Current Index | Previous Index | % Reporting Increase | % Reporting No Change | % Reporting Decrease |
Loan volume | 0.0 | 8.6 | 25.9 | 48.3 | 25.9 |
Nonperforming loans | –1.7 | –5.1 | 8.6 | 81.0 | 10.3 |
| Indicator | Current Index | Previous Index | % Reporting Eased | % Reporting No Change | % Reporting Tightened |
Credit standards and terms | –5.2 | –1.7 | 0.0 | 94.8 | 5.2 |
| Consumer Loans: Over the past six weeks, how have the following changed? | |||||
| Indicator | Current Index | Previous Index | % Reporting Increase | % Reporting No Change | % Reporting Decrease |
Loan volume | –10.0 | 1.7 | 16.7 | 56.7 | 26.7 |
Nonperforming loans | 0.0 | –4.9 | 8.2 | 83.6 | 8.2 |
| Indicator | Current Index | Previous Index | % Reporting Eased | % Reporting No Change | % Reporting Tightened |
Credit standards and terms | –3.3 | 0.0 | 1.6 | 93.4 | 4.9 |
| Banking Outlook: What is your expectation for the following items six months from now? | |||||
| Indicator | Current Index | Previous Index | % Reporting Increase | % Reporting No Change | % Reporting Decrease |
Total loan demand | –1.6 | 40.3 | 36.1 | 26.2 | 37.7 |
Nonperforming loans | 16.6 | 6.5 | 28.3 | 60.0 | 11.7 |
| General Business Activity: What is your evaluation of the level of activity? | |||||
| Indicator | Current Index | Previous Index | % Reporting Better | % Reporting No Change | % Reporting Worse |
Over the past six weeks | 3.3 | 29.0 | 29.5 | 44.3 | 26.2 |
Six months from now | –14.8 | 24.2 | 21.3 | 42.6 | 36.1 |
Survey participants are given the opportunity to submit comments on current issues that may be affecting their businesses. Some comments have been edited for grammar and clarity.
- The prolonged impact of the Iran war, inflationary pressures and higher interest rates are causing commercial and industrial customers to be cautious, and homebuying-mortgage activity has also slowed. New commercial real estate development activity remains healthy, but we could start to see negative effects of higher rates slow this sector.
- One of our biggest concerns is still increasing rates.
- I expect business activity to remain slightly above current levels over the next six months, supported by continued lending activity, business investment and favorable financial performance. However, changes in Federal Reserve policy expectations, ongoing inflation concerns, geopolitical uncertainty and energy market volatility present risks that could slow economic momentum.
- Loan opportunities fell off a cliff in August. Higher inflation is taking its toll.
- Rising interest rates are now affecting loan pricing in a big way.
- Higher interest rates concern me going forward. I think it will slow business activity and therefore loan demand may go down because of it. However, I still think our credit quality will remain strong.
- We have a corporation spending $50 billion on a data center in our area that is driving lots of growth and money flowing into our rural economy that has never happened before.
- We think because of increased Treasury yields, borrowing rates, gas and diesel prices, there will be an economic slowdown.
- Continuing to monitor the external economic environment, as the level of uncertainty and inflation can be viewed as impactful to current activity and challenging from a planning standpoint
Historical data can be downloaded dating back to March 2017. For the definitions, see data definitions.
NOTE: The following series were discontinued in May 2020: volume of core deposits, cost of funds, non-interest income and net interest margin.
Questions regarding the Banking Conditions Survey can be addressed to Mariam Yousuf at mariam.yousuf@dal.frb.org.
Sign up for our email alert to be automatically notified as soon as the latest Banking Conditions Survey is released on the web.