Banking Conditions Survey


For this survey, Eleventh District banking executives were asked supplemental questions on outlook concerns, core deposits, lending standards, and restrictions on AI agentic activity. Read the special questions results.
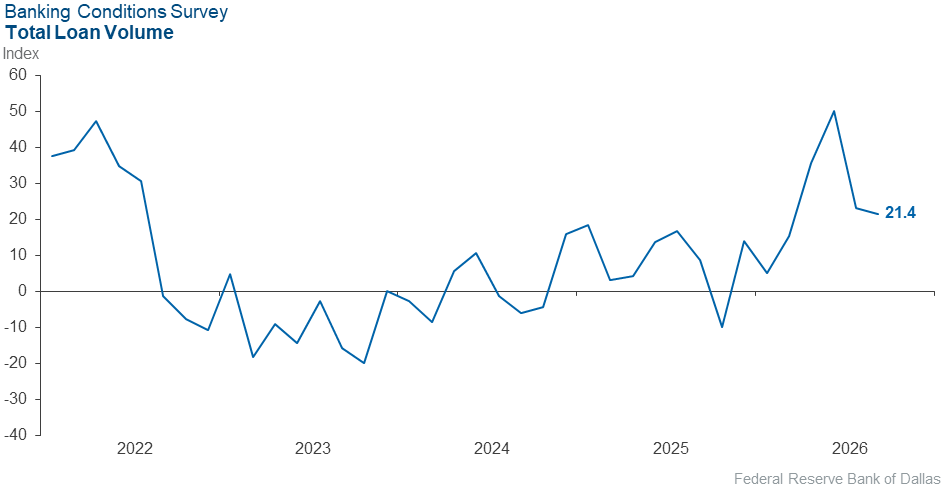
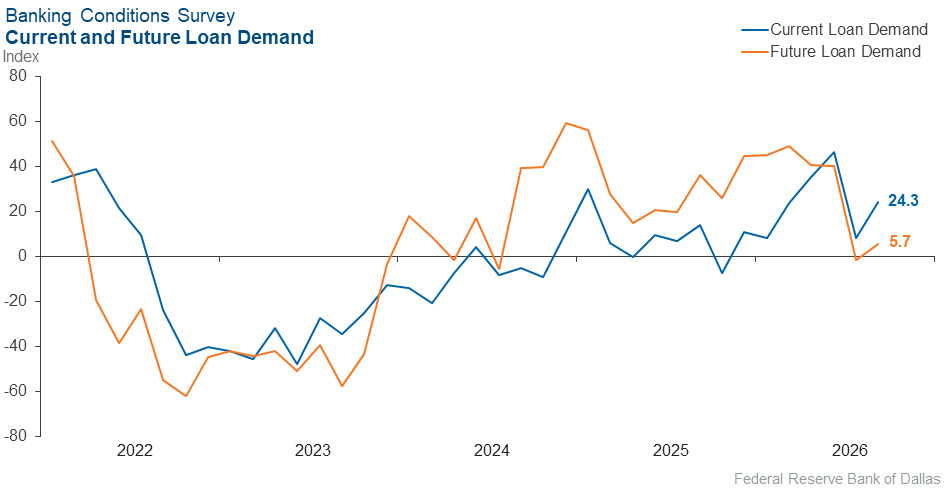
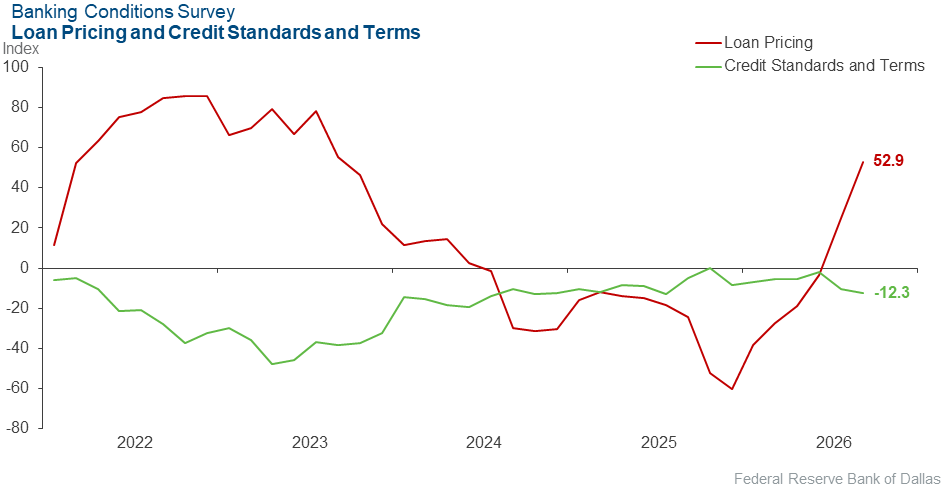
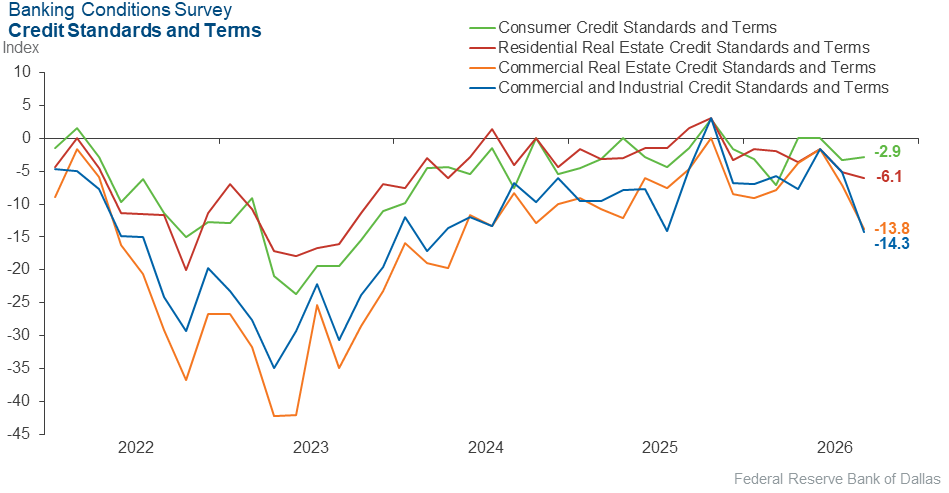
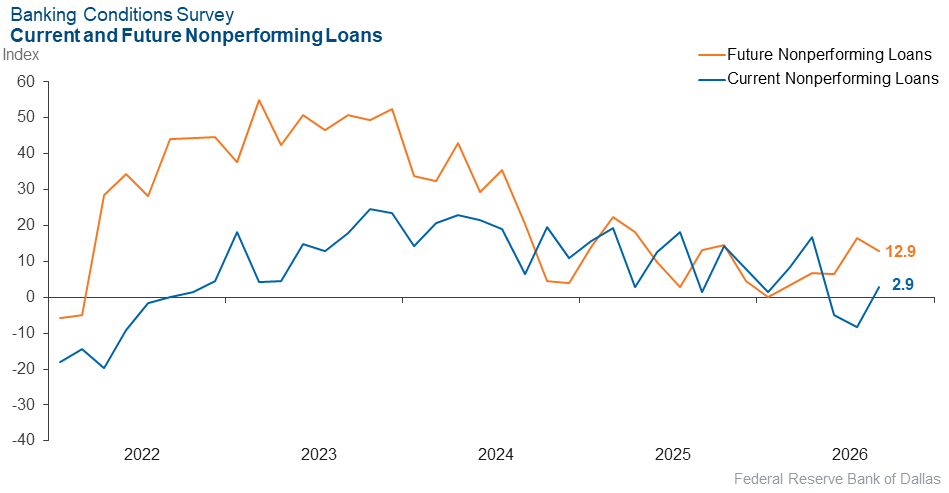
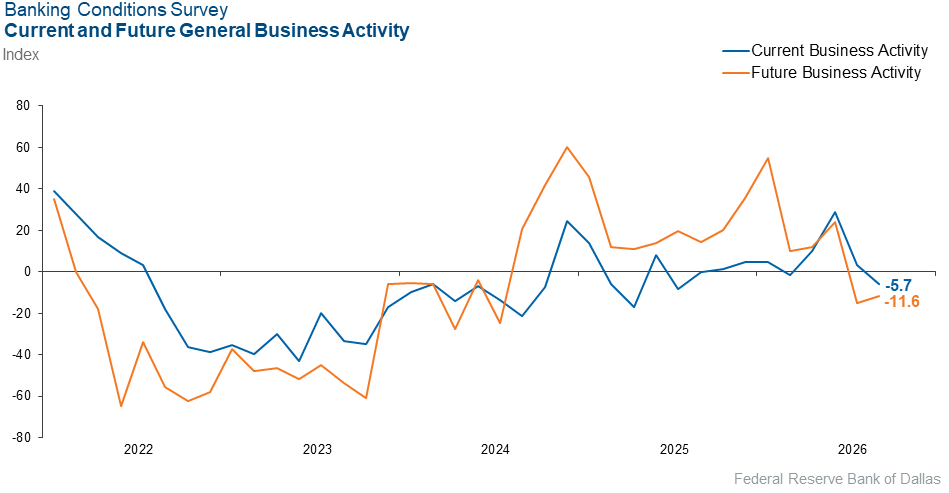
Loan volume continued to grow at the same pace as the prior period. Credit standards and terms tightened, and loan pricing increased broadly. Despite the higher interest rate, loan demand increased further. Overall loan performance weakened slightly after having improved for the last two surveys. Bankers reported a decrease in general business activity on net. Outlooks are mixed. Survey respondents expect an increase in loan demand but a decline in business activity six months from now, as well as a deterioration in loan performance.
Next release: December 29, 2026
Data were collected October 27–November 4, and 70 financial institutions responded to the survey. The Federal Reserve Bank of Dallas conducts the Banking Conditions Survey twice each quarter to obtain a timely assessment of activity at banks and credit unions headquartered in the Eleventh Federal Reserve District. CEOs or senior loan officers of financial institutions report on how conditions have changed for indicators such as loan volume, nonperforming loans and loan pricing. Respondents are also asked to report on their banking outlook and their evaluation of general business activity.
Survey responses are used to calculate an index for each indicator. Each index is calculated by subtracting the percentage of respondents reporting a decrease (or tightening) from the percentage reporting an increase (or easing). When the share of respondents reporting an increase exceeds the share reporting a decrease, the index will be greater than zero, suggesting the indicator has increased over the prior reporting period. If the share of respondents reporting a decrease exceeds the share reporting an increase, the index will be below zero, suggesting the indicator has decreased over the prior reporting period. An index will be zero when the number of respondents reporting an increase is equal to the number reporting a decrease.
Results summary
Historical data are available from March 2017.
| Total Loans: Over the past six weeks, how have the following changed? | |||||
| Indicator | Current Index | Previous Index | % Reporting Increase | % Reporting No Change | % Reporting Decrease |
Loan volume | 21.4 | 23.0 | 45.7 | 30.0 | 24.3 |
Loan demand | 24.3 | 8.2 | 48.6 | 27.1 | 24.3 |
Nonperforming loans | 2.9 | –8.2 | 18.6 | 65.7 | 15.7 |
Loan pricing | 52.9 | 25.0 | 54.3 | 44.3 | 1.4 |
| Indicator | Current Index | Previous Index | % Reporting Eased | % Reporting No Change | % Reporting Tightened |
Credit standards and terms | –12.3 | –10.4 | 0.0 | 87.7 | 12.3 |
| Commercial and Industrial Loans: Over the past six weeks, how have the following changed? | |||||
| Indicator | Current Index | Previous Index | % Reporting Increase | % Reporting No Change | % Reporting Decrease |
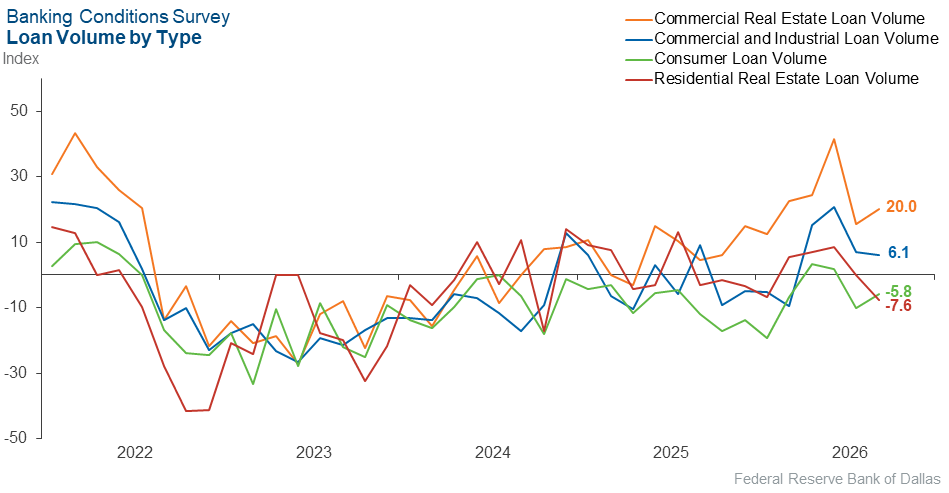
Loan volume | 6.1 | 6.9 | 24.6 | 56.9 | 18.5 |
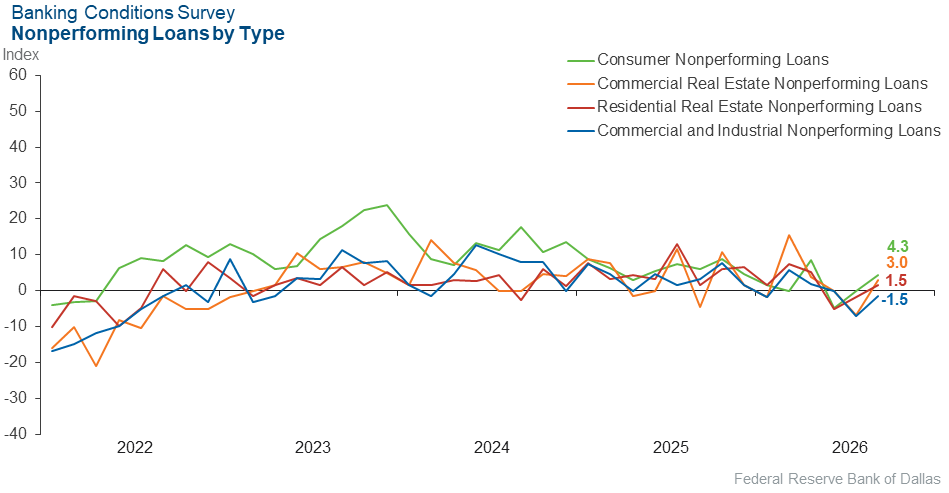
Nonperforming loans | –1.5 | –7.0 | 7.7 | 83.1 | 9.2 |
| Indicator | Current Index | Previous Index | % Reporting Eased | % Reporting No Change | % Reporting Tightened |
Credit standards and terms | –14.3 | –5.2 | 0.0 | 85.7 | 14.3 |
| Commercial Real Estate Loans: Over the past six weeks, how have the following changed? | |||||
| Indicator | Current Index | Previous Index | % Reporting Increase | % Reporting No Change | % Reporting Decrease |
Loan volume | 20.0 | 15.5 | 36.9 | 46.2 | 16.9 |
Nonperforming loans | 3.0 | –6.9 | 13.8 | 75.4 | 10.8 |
| Indicator | Current Index | Previous Index | % Reporting Eased | % Reporting No Change | % Reporting Tightened |
Credit standards and terms | –13.8 | –7.1 | 0.0 | 86.2 | 13.8 |
| Residential Real Estate Loans: Over the past six weeks, how have the following changed? | |||||
| Indicator | Current Index | Previous Index | % Reporting Increase | % Reporting No Change | % Reporting Decrease |
Loan volume | –7.6 | 0.0 | 21.2 | 50.0 | 28.8 |
Nonperforming loans | 1.5 | –1.7 | 10.6 | 80.3 | 9.1 |
| Indicator | Current Index | Previous Index | % Reporting Eased | % Reporting No Change | % Reporting Tightened |
Credit standards and terms | –6.1 | –5.2 | 0.0 | 93.9 | 6.1 |
| Consumer Loans: Over the past six weeks, how have the following changed? | |||||
| Indicator | Current Index | Previous Index | % Reporting Increase | % Reporting No Change | % Reporting Decrease |
Loan volume | –5.8 | –10.0 | 14.5 | 65.2 | 20.3 |
Nonperforming loans | 4.3 | 0.0 | 10.1 | 84.1 | 5.8 |
| Indicator | Current Index | Previous Index | % Reporting Eased | % Reporting No Change | % Reporting Tightened |
Credit standards and terms | –2.9 | –3.3 | 1.4 | 94.2 | 4.3 |
| Banking Outlook: What is your expectation for the following items six months from now? | |||||
| Indicator | Current Index | Previous Index | % Reporting Increase | % Reporting No Change | % Reporting Decrease |
Total loan demand | 5.7 | –1.6 | 40.0 | 25.7 | 34.3 |
Nonperforming loans | 12.9 | 16.6 | 28.6 | 55.7 | 15.7 |
| General Business Activity: What is your evaluation of the level of activity? | |||||
| Indicator | Current Index | Previous Index | % Reporting Better | % Reporting No Change | % Reporting Worse |
Over the past six weeks | –5.7 | 3.3 | 28.6 | 37.1 | 34.3 |
Six months from now | –11.6 | –14.8 | 23.2 | 42.0 | 34.8 |
Survey participants are given the opportunity to submit comments on current issues that may be affecting their businesses. Some comments have been edited for grammar and clarity.
- One of our biggest concerns is increasing rates which puts pressure on our margins. Other concerns are the November midterm elections and the stabilization of oil prices.
- We are starting to see an increase in loan opportunities in commercial and industrial and commercial real estate.
- General business activity has improved but residential real estate has worsened.
- Potential higher interest rates will cause volume to slow and could slow business activity altogether.
- I am worried that if rates keep going up, some customers may have trouble making payments.
- Immigration [slowdown] is having significant repercussions in the [Rio Grande] Valley.
- [We are] continuing to see evidence of a K-shaped economy with a portion of strong credit [quality] loans driving lending, partially offset by consumers adversely impacted by economic stress and inflation.
Historical data can be downloaded dating back to March 2017. For the definitions, see data definitions.
NOTE: The following series were discontinued in May 2020: volume of core deposits, cost of funds, non-interest income and net interest margin.
Questions regarding the Banking Conditions Survey can be addressed to Mariam Yousuf at mariam.yousuf@dal.frb.org.
Sign up for our email alert to be automatically notified as soon as the latest Banking Conditions Survey is released on the web.