Special Questions

Special Questions
For this month’s survey, Texas business executives were asked supplemental questions on credit conditions. Results below include responses from participants from both the Texas Manufacturing Outlook Survey and Texas Service Sector Outlook Survey.
Texas Business Outlook Surveys
Data were collected Oct. 13–21, and 283 Texas business executives responded to the surveys.
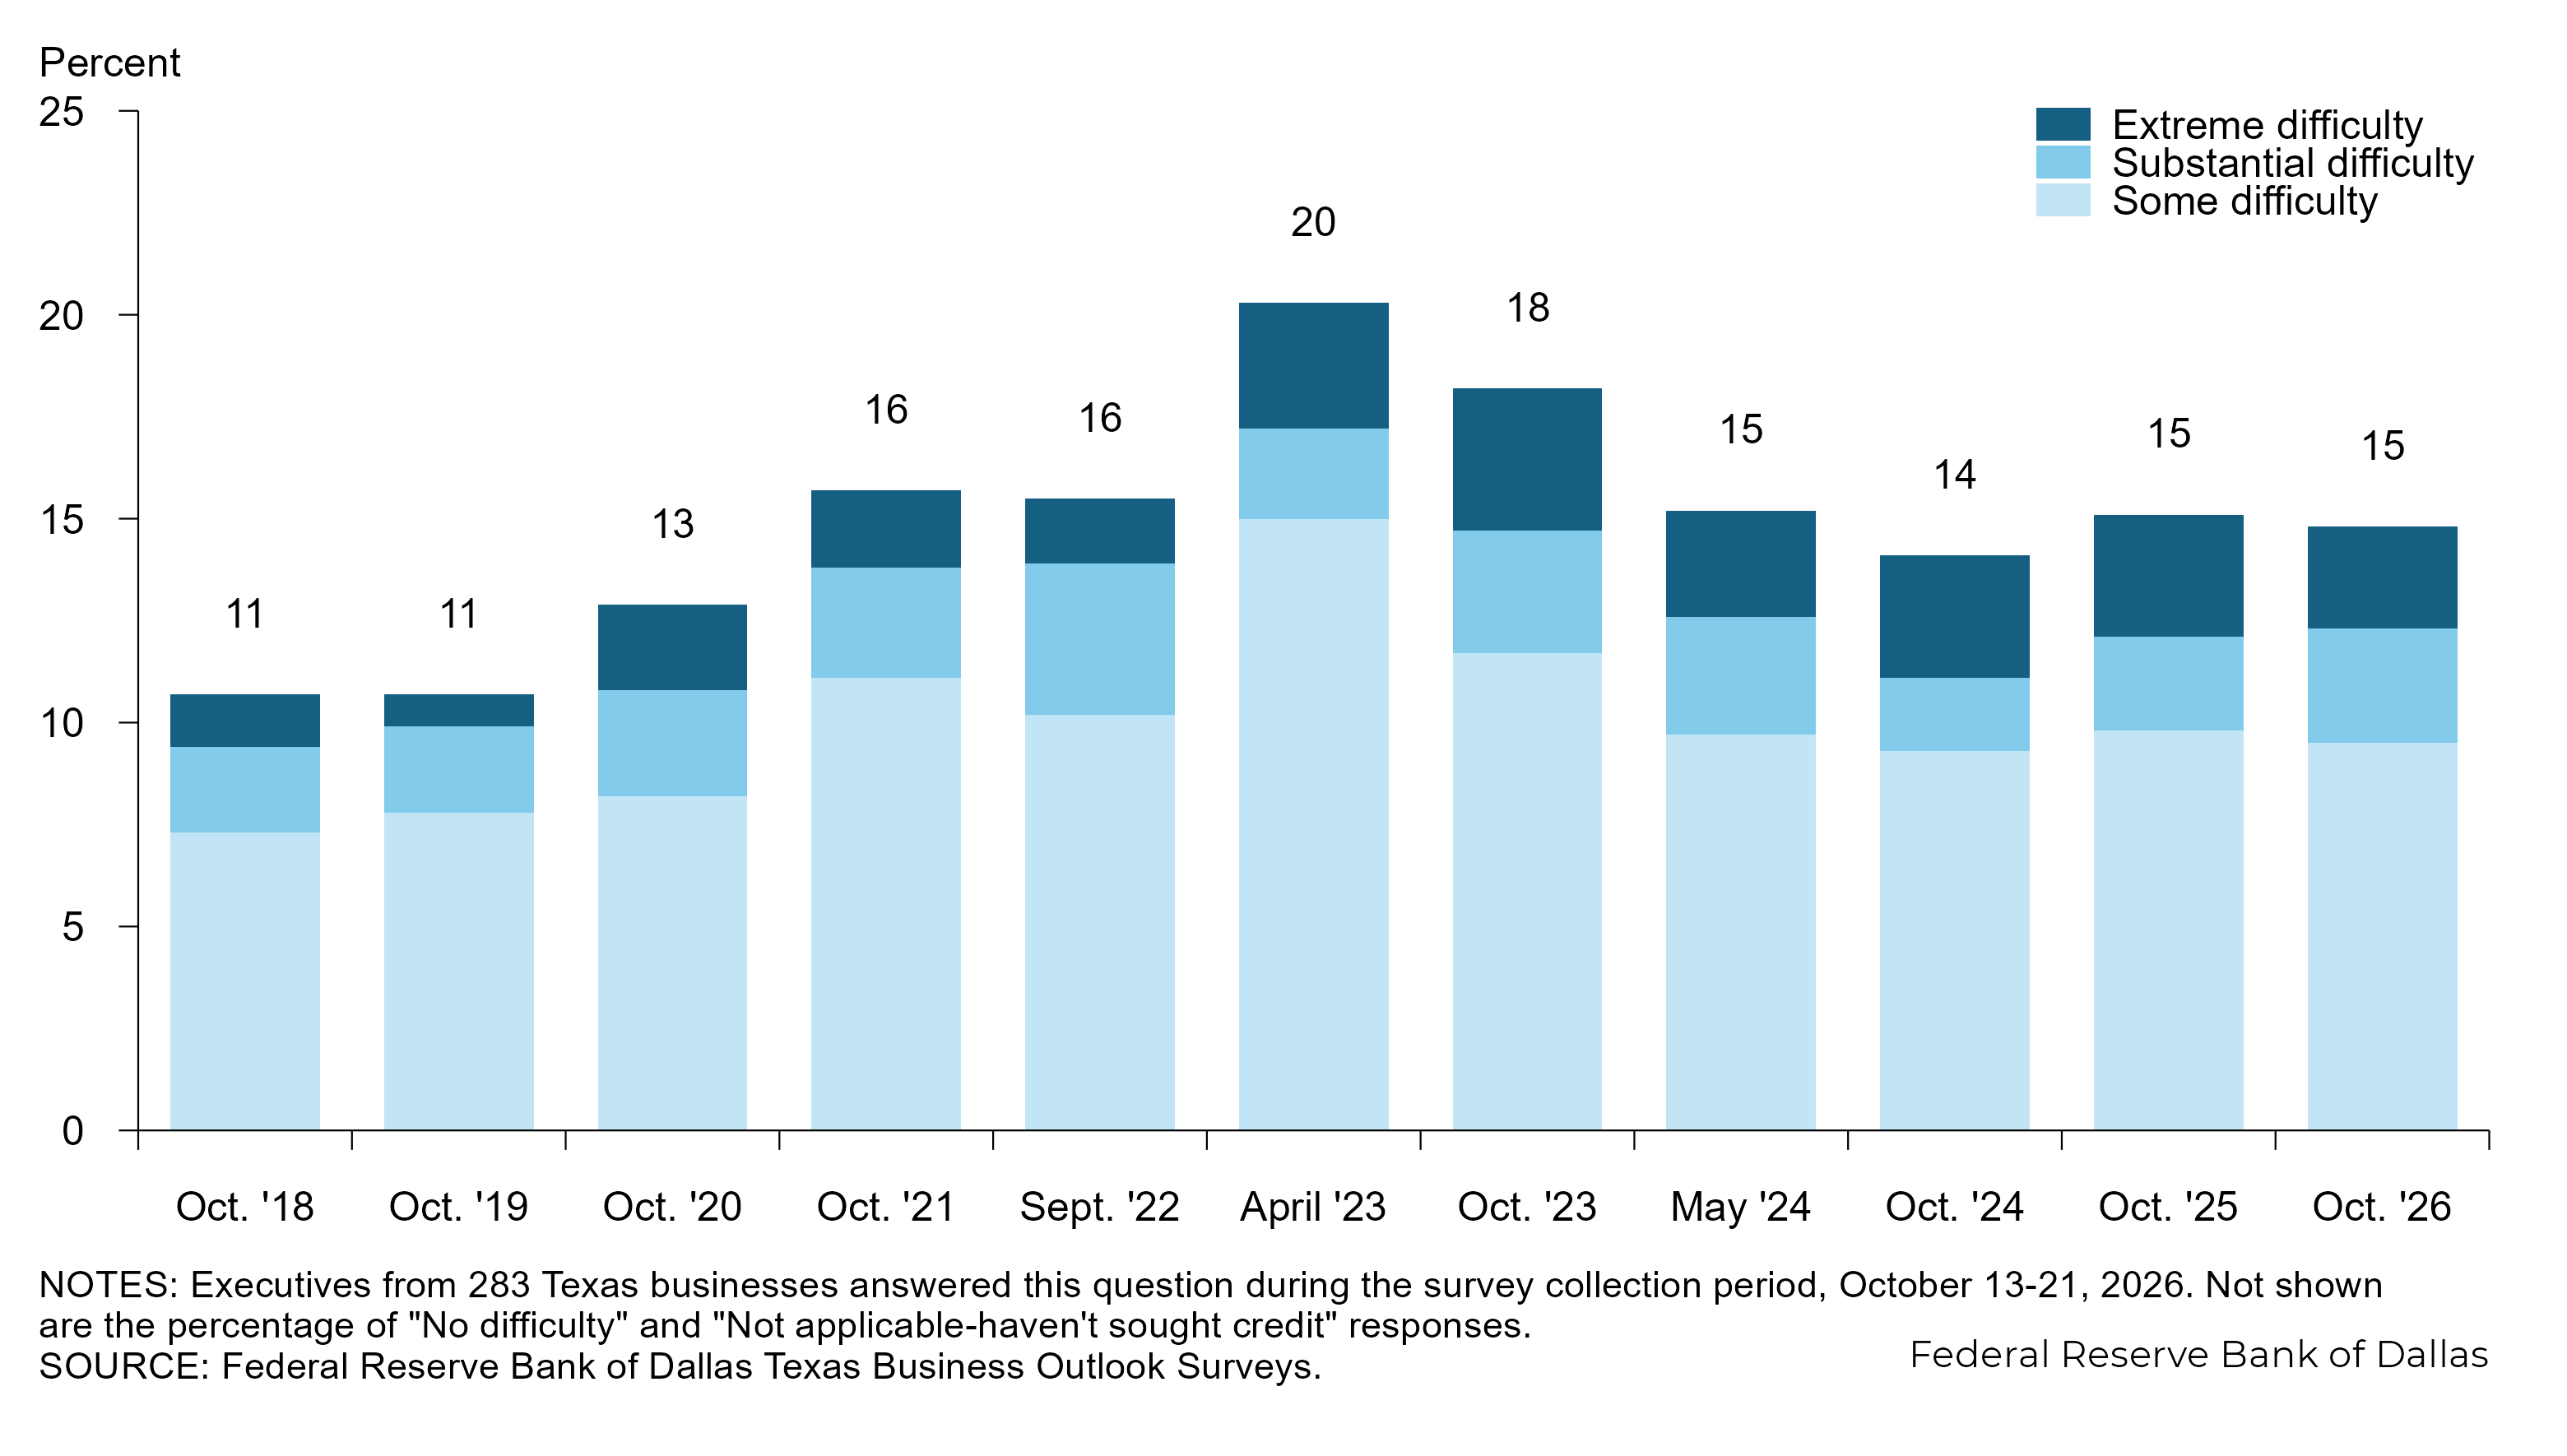
Fifteen percent of responding Texas businesses say they are having at least some difficulty accessing short-term credit, unchanged from a year ago. The share is down from a peak of 20 percent in April 2023 but above the prepandemic results in 2018-19.
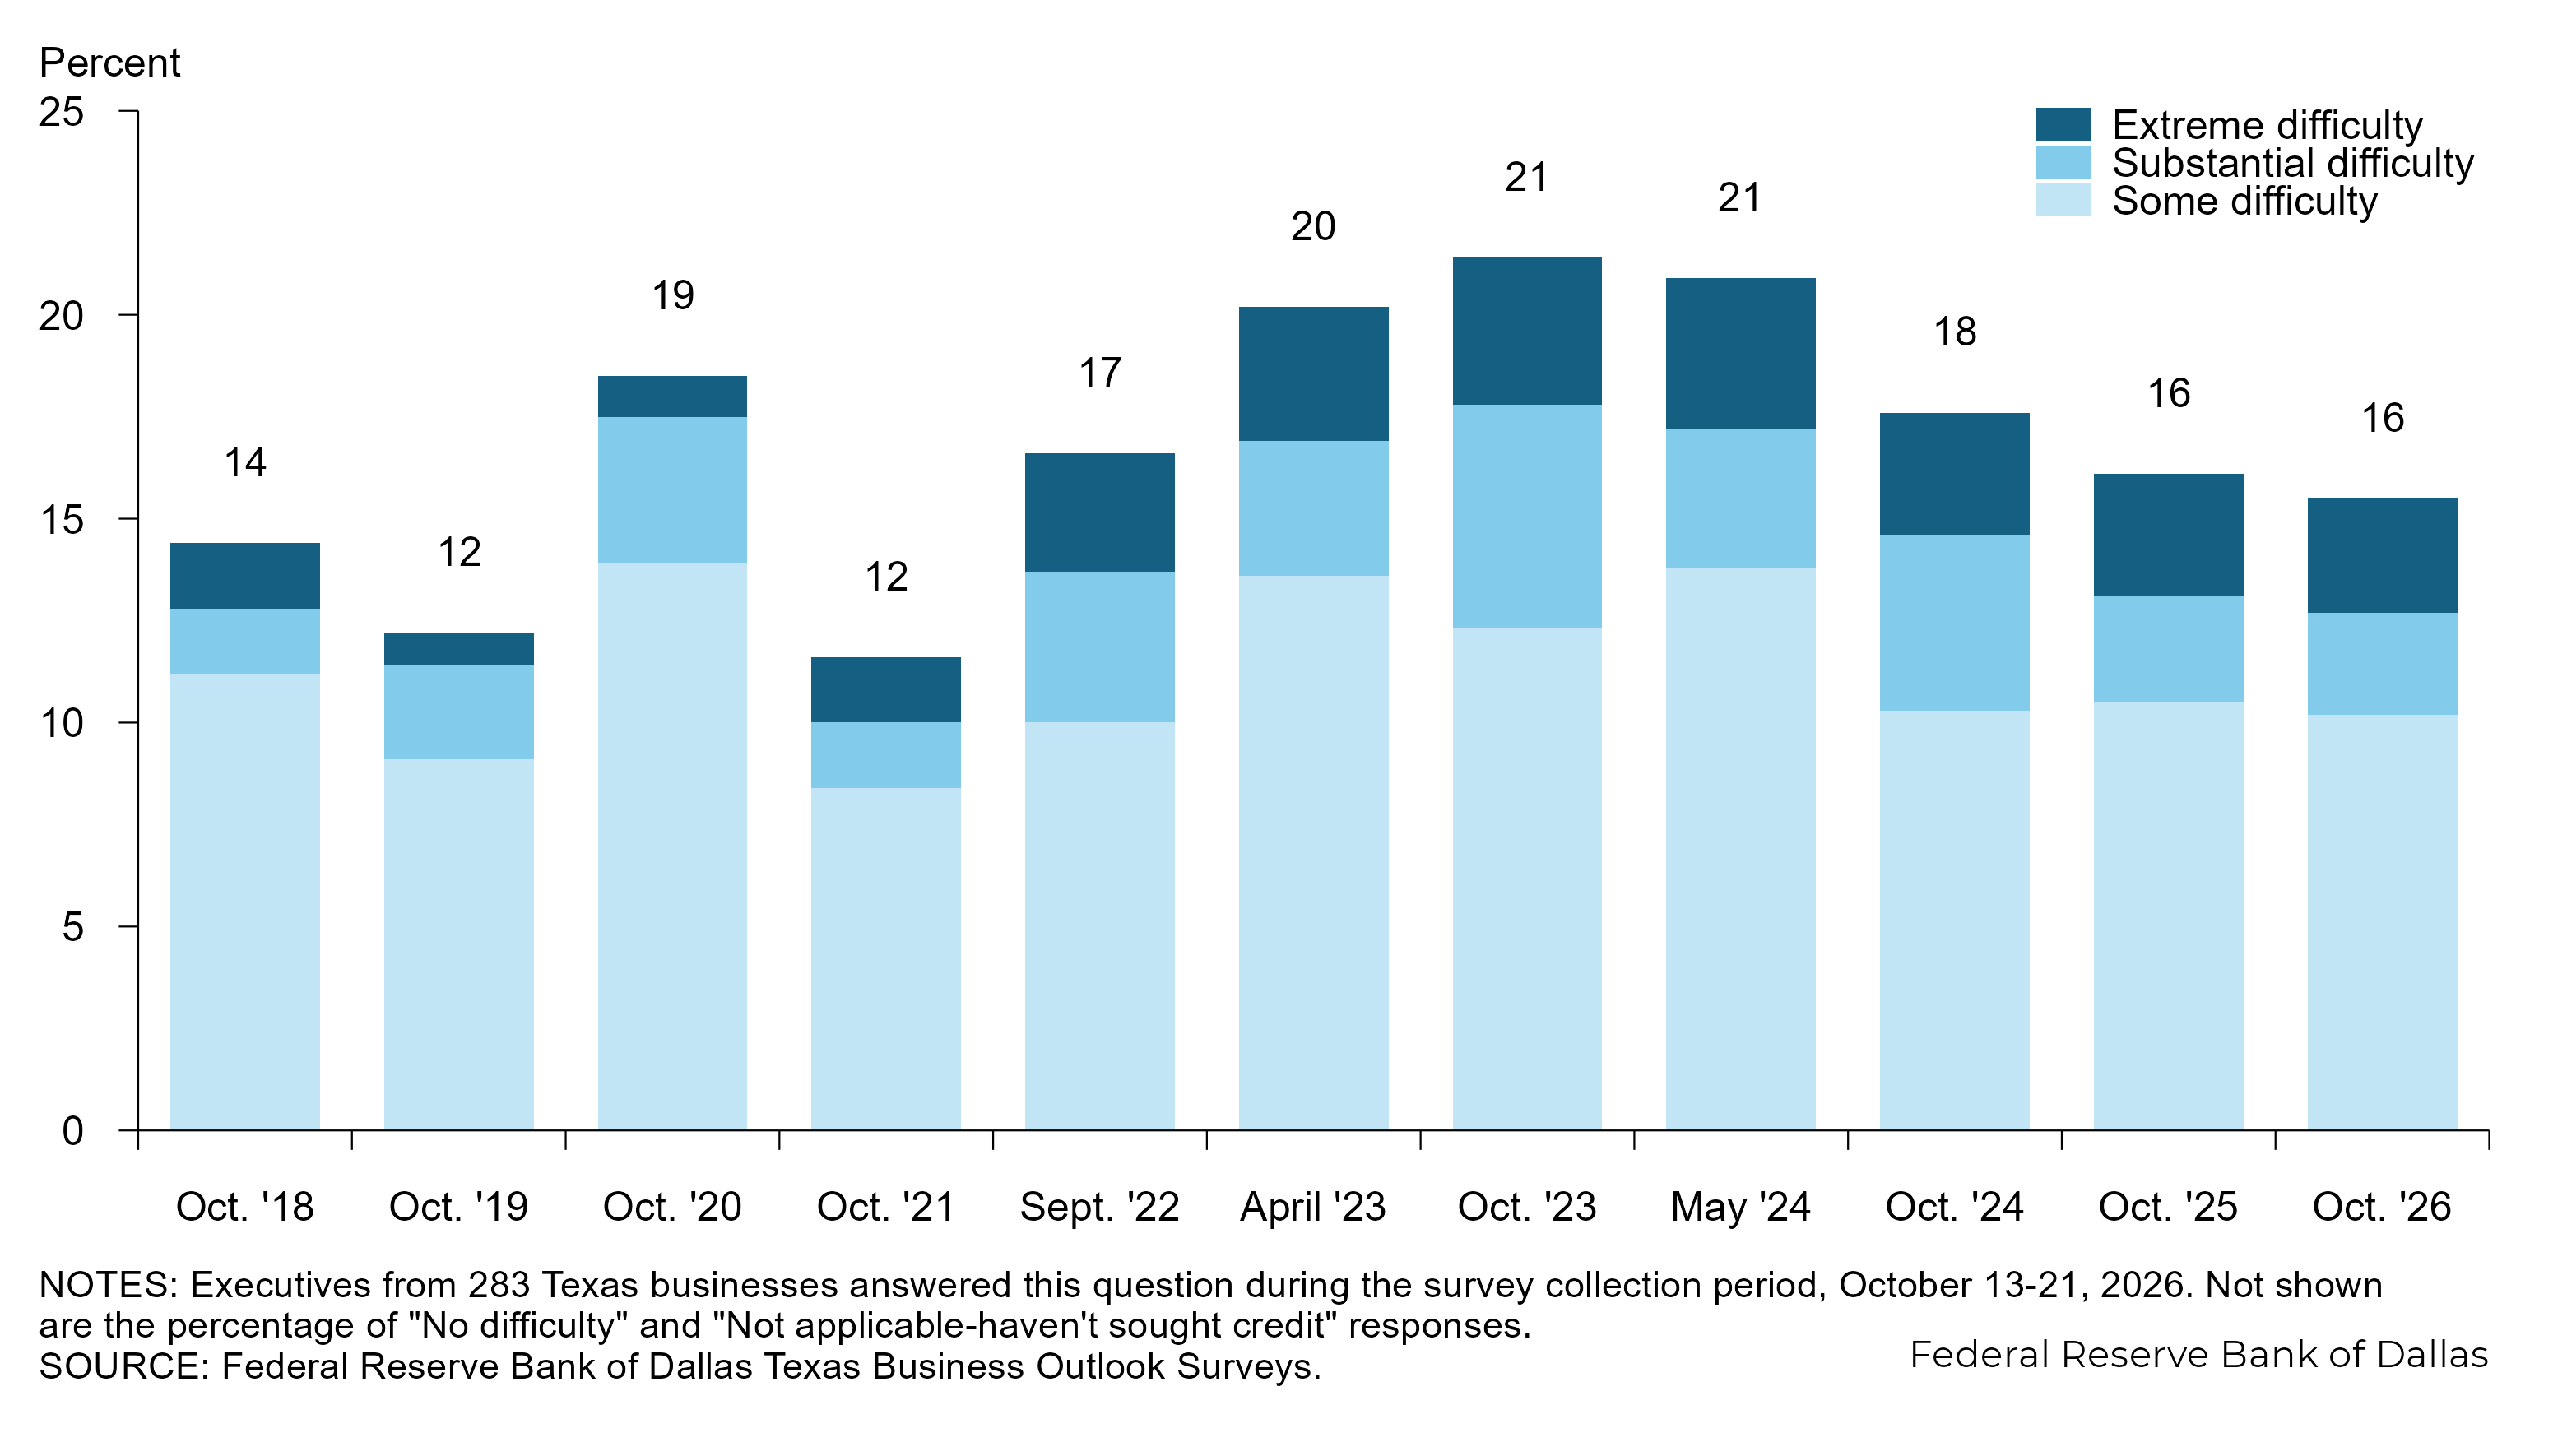
Similarly, 16 percent of responding Texas businesses say they are having at least some difficulty accessing long-term credit. This is the same as a year ago and down from a peak of 21 percent in 2023, and somewhat elevated relative to 2018-19.
More than a third of business executives note an increase in the cost of credit over the past year. The majority either did not access credit or noted no change in cost.
| Oct. '26 (percent) |
||
| Increased | 35.3 | |
| No change | 18.0 | |
| Decreased | 0.4 | |
| Not applicable | 46.3 | |
| Note: 283 responses | ||
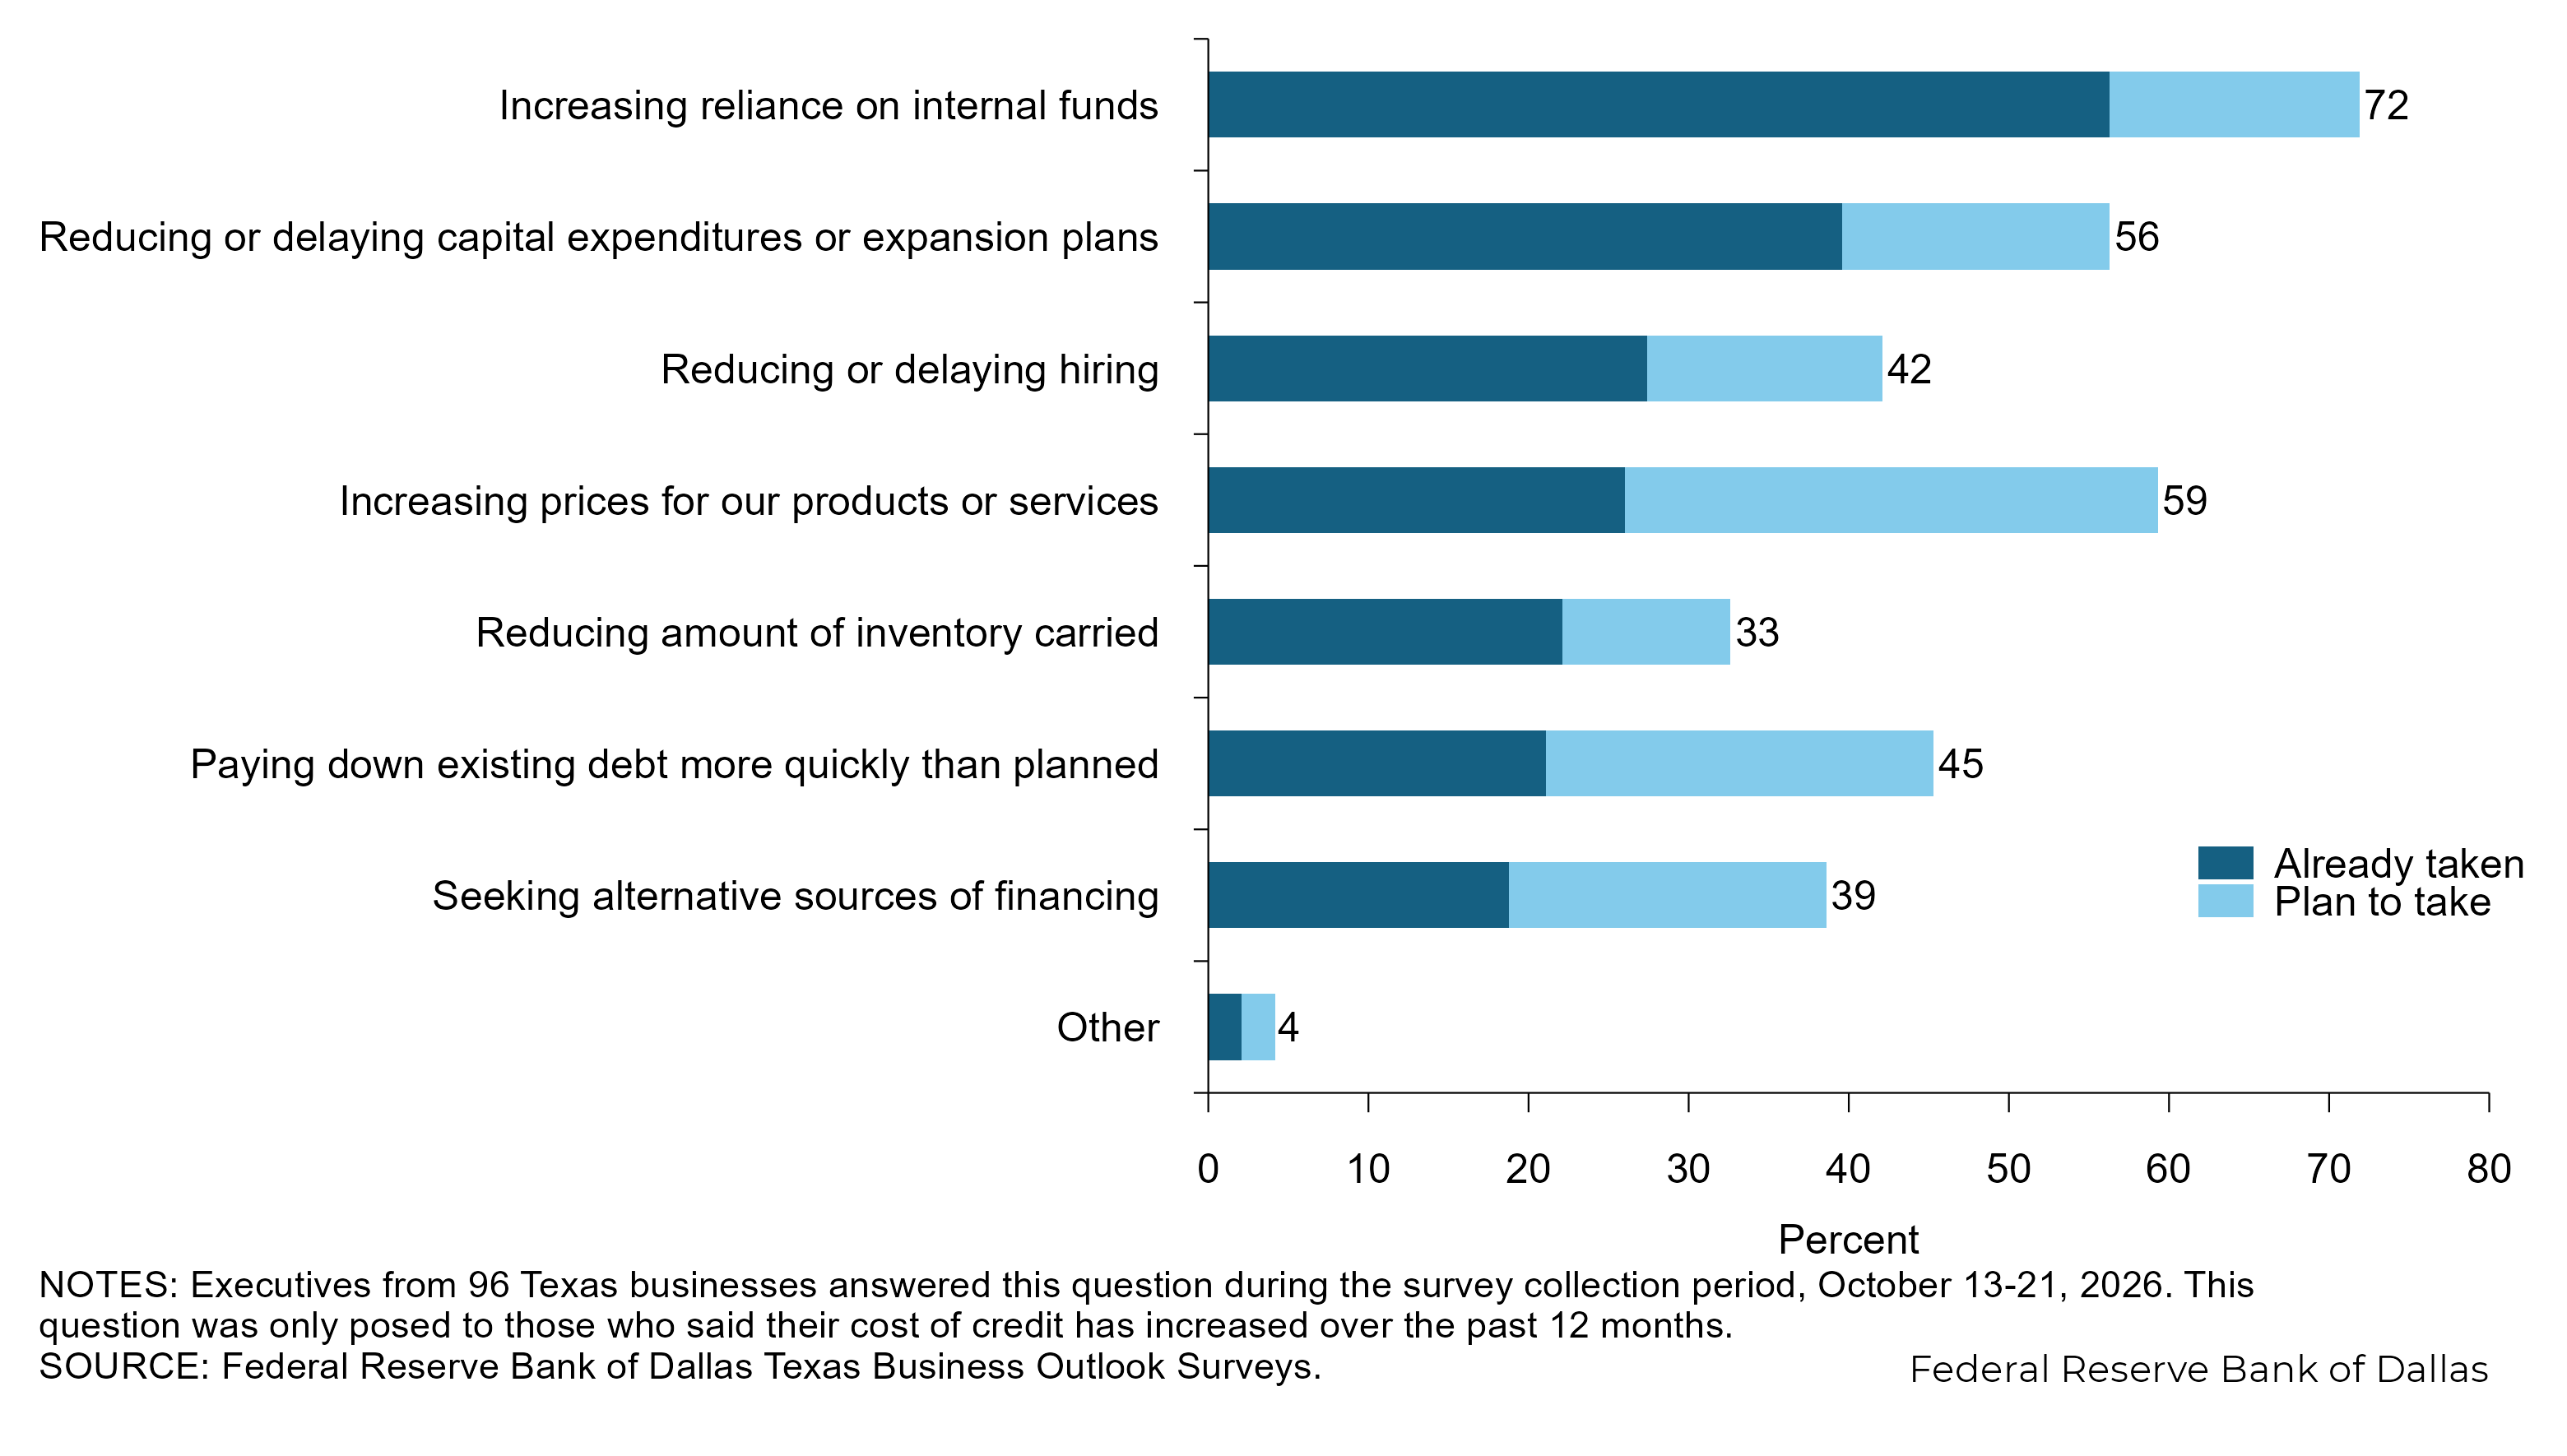
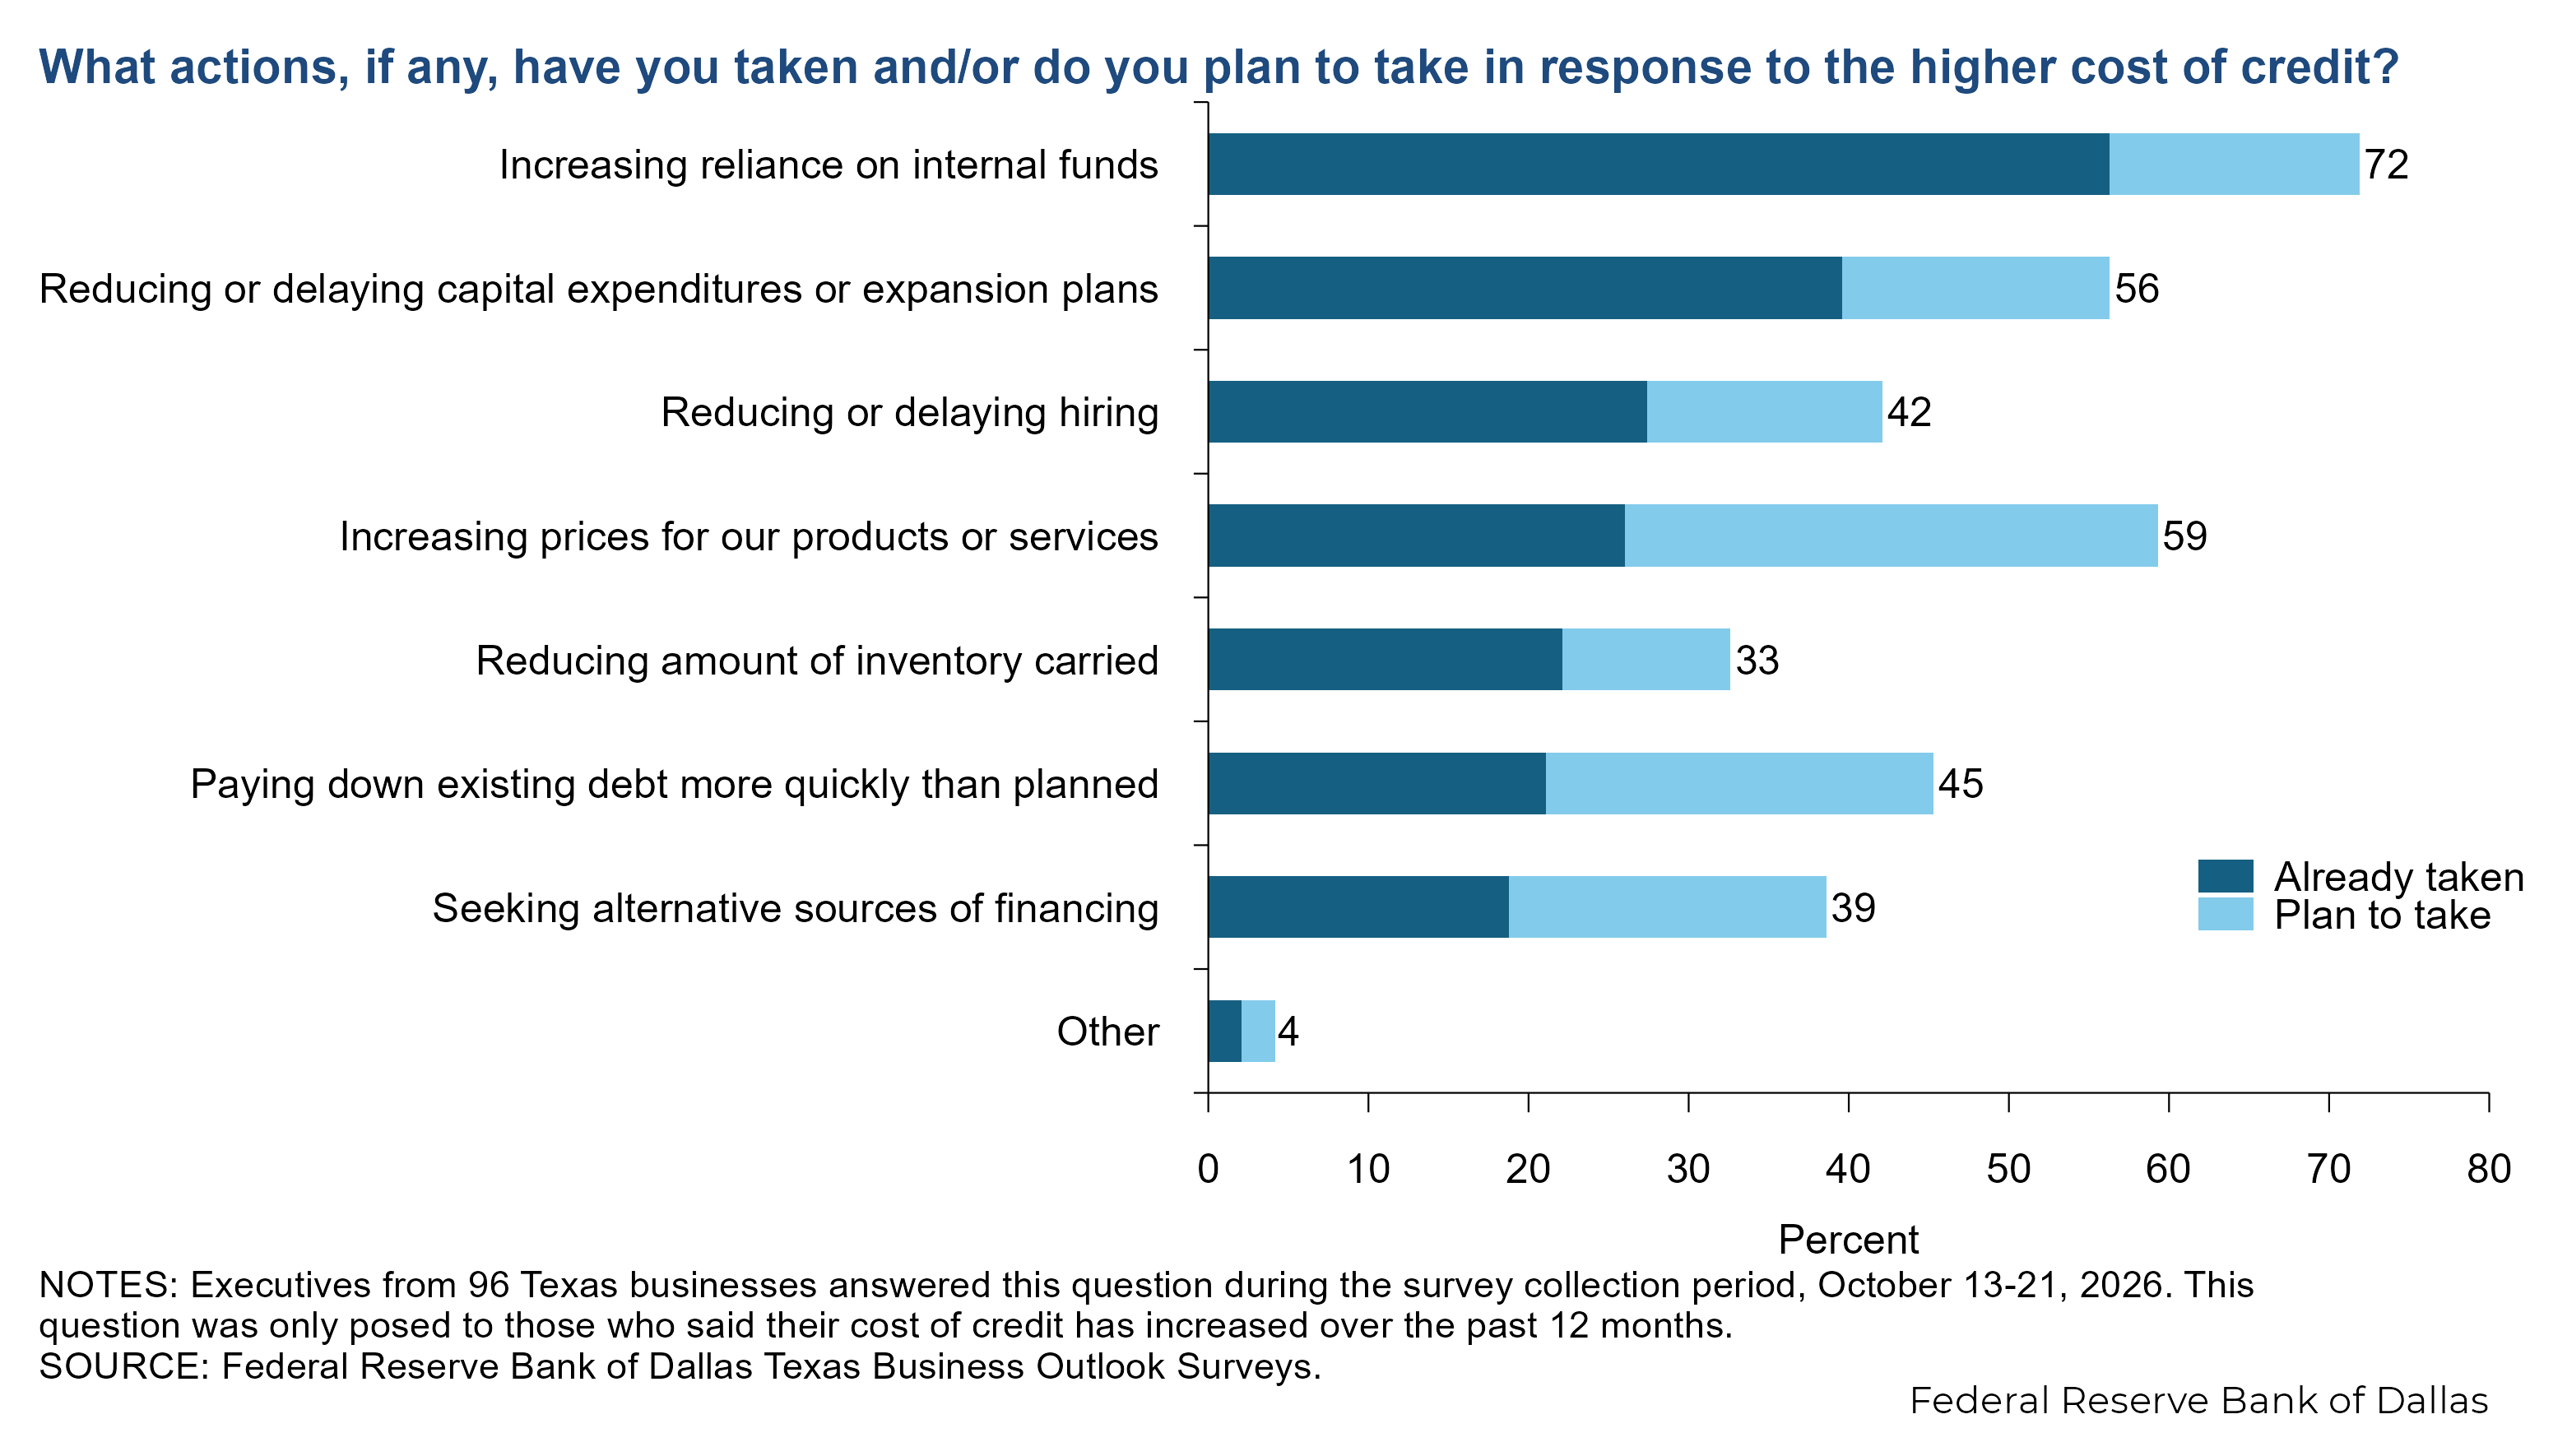
Among Texas firms noting an increase in the cost of credit over the past year, more than half increased their reliance on internal funds in response. Forty percent pulled back on capital expenditures and just over a quarter pulled back on hiring or increased prices for their products or services.
Survey respondents were given the opportunity to also provide comments, which can be found in the Comments tab above.
Texas Manufacturing Outlook Survey
Data were collected Oct. 13-21, and 63 Texas manufacturers responded to the survey.
| Oct. '20 (percent) |
Oct. '21 (percent) |
Sept. '22 (percent) |
Oct. '23 (percent) |
Oct. '24 (percent) |
Oct. '25 (percent) |
Oct. '26 (percent) |
|
| No difficulty | 51.1 | 48.0 | 47.1 | 42.9 | 37.8 | 31.9 | 31.7 |
| Some difficulty | 8.9 | 7.0 | 9.2 | 4.4 | 9.8 | 13.9 | 9.5 |
| Substantial difficulty | 6.7 | 6.0 | 4.6 | 1.1 | 3.7 | 1.4 | 4.8 |
| Extreme difficulty | 0.0 | 4.0 | 1.1 | 5.5 | 2.4 | 2.8 | 3.2 |
| Not applicable—haven’t sought credit | 33.3 | 35.0 | 37.9 | 46.2 | 46.3 | 50.0 | 50.8 |
NOTES: 63 responses.
| Oct. '20 (percent) |
Oct. '21 (percent) |
Sept. '22 (percent) |
Oct. '23 (percent) |
Oct. '24 (percent) |
Oct. '25 (percent) |
Oct. '26 (percent) |
|
| No difficulty | 51.1 | 60.0 | 51.7 | 36.3 | 44.4 | 30.6 | 31.7 |
| Some difficulty | 13.3 | 4.0 | 8.0 | 14.3 | 4.9 | 13.9 | 14.3 |
| Substantial difficulty | 6.7 | 3.0 | 1.1 | 3.3 | 6.2 | 2.8 | 0.0 |
| Extreme difficulty | 0.0 | 4.0 | 4.6 | 3.3 | 4.9 | 0.0 | 6.3 |
| Not applicable—haven’t sought credit | 28.9 | 29.0 | 34.5 | 42.9 | 39.5 | 52.8 | 47.6 |
NOTE: 63 responses.
| Oct. '26 (percent) |
|
| Increased | 41.3 |
| No change | 20.6 |
| Decreased | 0.0 |
| Not applicable | 38.1 |
NOTE: 63 responses.
| Already taken (percent) |
Plan to take (percent) |
Not taking/not applicable (percent) |
|
| Increasing reliance on internal funds | 56.0 | 16.0 | 28.0 |
| Reducing or delaying capital expenditures or expansion plans | 44.0 | 12.0 | 44.0 |
| Reducing or delaying hiring | 33.3 | 4.2 | 62.5 |
| Reducing amount of inventory carried | 25.0 | 20.8 | 54.2 |
| Increasing prices for our products or services | 20.0 | 40.0 | 40.0 |
| Seeking alternative sources of financing | 16.0 | 12.0 | 72.0 |
| Paying down existing debt more quickly than planned | 8.3 | 29.2 | 62.5 |
| Other | 4.0 | 0.0 | 96.0 |
NOTES: 25 responses. This question was only posed to those who said their cost of credit has increased over the past 12 months.
Survey respondents were given the opportunity to also provide comments, which can be found in the Comments tab above.
Texas Service Sector Outlook Survey
Data were collected Oct. 13-21, and 220 Texas business executives responded to the survey.
| Oct. '20 (percent) |
Oct. '21 (percent) |
Sept. '22 (percent) |
Oct. '23 (percent) |
Oct. '24 (percent) |
Oct. '25 (percent) |
Oct. '26 (percent) |
|
| No difficulty | 38.9 | 40.6 | 35.4 | 29.6 | 32.0 | 33.9 | 29.1 |
| Some difficulty | 8.1 | 12.5 | 10.5 | 14.1 | 9.2 | 8.6 | 9.5 |
| Substantial difficulty | 1.3 | 1.5 | 3.4 | 3.6 | 1.2 | 2.6 | 2.3 |
| Extreme difficulty | 2.7 | 1.1 | 1.7 | 2.9 | 3.2 | 3.0 | 2.3 |
| Not applicable—haven’t sought credit | 49.0 | 44.3 | 49.0 | 49.8 | 54.4 | 51.9 | 56.8 |
NOTES: 220 responses.
| Oct. '20 (percent) |
Oct. '21 (percent) |
Sept. '22 (percent) |
Oct. '23 (percent) |
Oct. '24 (percent) |
Oct. '25 (percent) |
Oct. '26 (percent) |
|
| No difficulty | 34.2 | 42.2 | 35.3 | 27.3 | 32.3 | 32.8 | 28.6 |
| Some difficulty | 14.1 | 10.0 | 10.6 | 11.6 | 12.1 | 9.5 | 9.1 |
| Substantial difficulty | 2.7 | 1.1 | 4.5 | 6.2 | 3.6 | 2.6 | 3.2 |
| Extreme difficulty | 1.3 | 0.7 | 2.4 | 3.6 | 2.4 | 3.9 | 1.8 |
| Not applicable—haven’t sought credit | 47.7 | 45.9 | 47.3 | 51.3 | 49.6 | 51.3 | 57.3 |
NOTE: 220 responses.
| Oct. '26 (percent) |
|
| Increased | 33.6 |
| No change | 17.3 |
| Decreased | 0.5 |
| Not applicable | 48.6 |
NOTE: 220 responses.
| Already taken (percent) |
Plan to take (percent) |
Not taking/not applicable (percent) |
|
| Increasing reliance on internal funds | 56.3 | 15.5 | 28.2 |
| Reducing or delaying capital expenditures or expansion plans | 38.0 | 18.3 | 43.7 |
| Increasing prices for our products or services | 28.2 | 31.0 | 40.8 |
| Reducing or delaying hiring | 25.4 | 18.3 | 56.3 |
| Paying down existing debt more quickly than planned | 25.4 | 22.5 | 52.1 |
| Reducing amount of inventory carried | 21.1 | 7.0 | 71.8 |
| Seeking alternative sources of financing | 19.7 | 22.5 | 57.7 |
| Other | 1.4 | 2.8 | 95.8 |
NOTES: 71 responses. This question was only posed to those who said their cost of credit has increased over the past 12 months.
Survey respondents were given the opportunity to also provide comments, which can be found in the Comments tab above.
Questions regarding the Texas Business Outlook Surveys can be addressed to Emily Kerr at emily.kerr@dal.frb.org.
Sign up for our email alert to be automatically notified as soon as the latest surveys are released on the web.
Special questions comments
Survey participants are given the opportunity to submit comments. Some comments have been edited for grammar and clarity.